Last Friday, the yield on the 10-year US Treasury note was a tiny bit less than that of the 3-month US Treasury bill. This is known as a yield inversion, and depending on which article you read, this specific type of yield inversion (10-year minus 3-month) has happened before each of the past 6, 7, or 9 recessions. More overview in this :
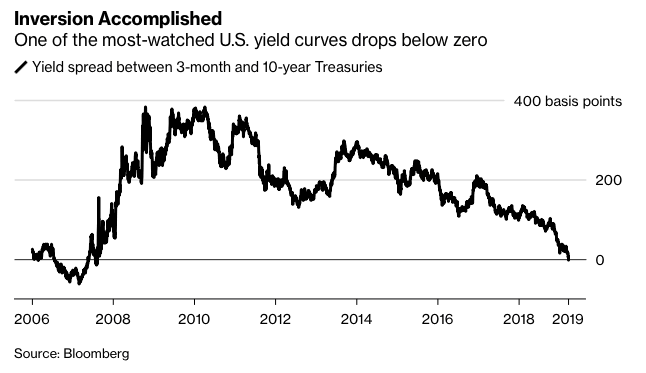
Here is a showing the difference between the 10-year and 3-month yields since 1978. The gray areas are recessions. (Click to enlarge.)
Yield inversion. Recession. Yield inversion. Recession. Every time.
This does not necessarily mean you should sell all your stocks now. You can see for yourself that there is a bit of lag time between the initial inversion and the official start of a recession. The length of time can vary, and it could be years. That means if you jump out of stocks now, things might still go up for a while. In addition, there’s no way to know the length or severity of the recession. How will you know when to jump back in stocks again? Lots of people sat out 2008 through 2018.
In my opinion, this is like your local fire department knocking on your door and reminding you to make an emergency plan for whatever disasters you are exposed to – fire, earthquakes, tornadoes, hurricanes. A hurricane may not hit soon, or even this year, or the next. You make the plan now, so you will be prepared and know exactly what to do when it does eventually hit.
You should know that you are going to do in a recession before the recession actually hits.
- What will you do if you lose your job and can find another one immediately? What if your business revenue drops significantly?
- Do you know what areas of spending you would cut if you really needed to? What can you liquidate easily for cash?
- What will you do if your stocks lose up to 50% in value and stay that way for years? Will you hold? Sell or rebalance according to a preset rule?
- What will you do if your home value drops by 20% or more?
- Where can you borrow money if needed? Are you sure that line of credit will still be there?
I’ve thought about most of this, but I should create a written plan that my partner can follow even if I’m not around.
“The editorial content here is not provided by any of the companies mentioned, and has not been reviewed, approved or otherwise endorsed by any of these entities. Opinions expressed here are the author’s alone.”
from .
Copyright © 2018 MyMoneyBlog.com. All Rights Reserved. Do not re-syndicate without permission.
Related Posts