Sometimes it seems like everyone just wants risk these days. Crypto. Sports gambling. Options trading, ETFs that magically yield 10% or more. However, if you’re in the opposite camp and you want the absolute least amount of risk, you’d want to retire off an investment that has a return that is fully-guaranteed, pays out a monthly income like clockwork, is even guaranteed to grow with inflation.
If that interests you, check out by Allan Roth – which first reminds you that Social Security is exactly this! – but also introduces a new series of .
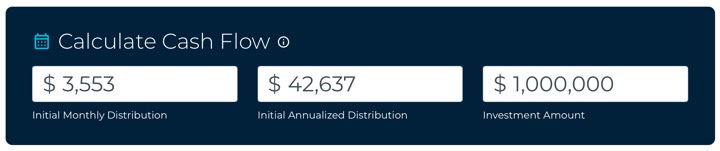
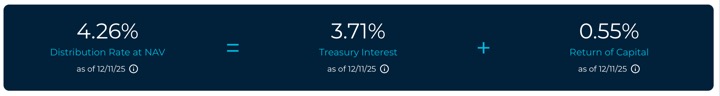
At current rates as of 12/11/25, the LifeX 2055 Inflation-Protected Longevity Income ETF () contains a managed portfolio of United States Treasury Inflation Indexed Bonds (TIPS) that can provide you with a 4.26% guaranteed real withdrawal rate for 30 years. That means a $1,000,000 portfolio would distribute roughly $42,600 in annual income for 30 years (through the year 2055), but importantly would increase with CPI inflation each year. At 3% average inflation, your 30th year’s income would have grown to over $100,000 a year.
After those 30 years, you will be left with nothing. Your initial principal will be gone. Therefore, your income taken each year is partially a return of principal.
The expense ratio is 0.25%, which isn’t Vanguard-level but not horrible. I like that it does all of the work for you in a tidy ETF package, as building a TIPS ladder yourself can be a bit tricky (and do you want to keep doing it at age 80, 90?). Of course, I also worry about what happens if you bought a 30-year ladder at 65 and happen to live past 95. It could happen, and remember, this product is meant for the risk-averse folks that like to cover all the bases.
In general, I feel a TIPS ladder or equivalent that adjusts with inflation would work well in combination with a traditional annuity like an SPIA or a deferred longevity annuity that starts at a later age, which doesn’t adjust with inflation but does provide an higher initial fixed income that can last as long as you live. This is what I have set up for my parents – Social Security that rises with inflation, plus a joint income annuity that pays out as long as one is living.
Related Posts