The WSJ article (free gift article) discusses new research using “deep learning” artificial intelligence to find the optimal asset allocation over time. There are several interesting insights that also agree with common sense. For example, one size doesn’t fit all. Wealthier investors can withstand the volatility from holding a much higher stock allocation, whereas lower net worth investors need to be more conservative to avoid a hitting zero due to a bad sequence of returns.
In addition, the average AI optimal glide path also differs from the average Target Date Fund:
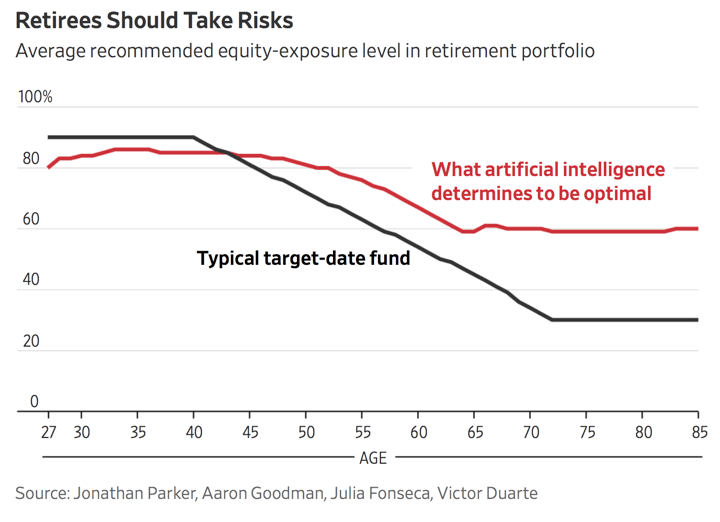
Though the primary insight of this modeling is that one size doesn’t fit all, the research did reach one conclusion that does apply to all of us on average: The typical glide path used by target-date funds is too conservative starting at the age of 50. In contrast to an equity exposure level that drops to 50% by retirement age and to as low as 30% during retirement, the average recommended equity exposure in the researchers’ model never falls below 60%.
While I don’t know the details regarding the underlying assumptions of this research, the red AI line caught my eye because I also don’t plan on going below about 60% stocks ever in my lifetime. My reasoning is that I am going for a “perpetual withdrawal rate” scenario where my I just live off a base of growing dividends and interest. (I’m not talking about owning only extreme high-yield products like closed-end ETFs, junk bonds, and leveraged REITs). After reaching the “safe withdrawal rate” number that is based on a very high likelihood of not dying with zero, I wanted even more margin of safety. It can be counterintuitive, but over the long run owning businesses can be “safer” than just own a big bag of cash that is constantly exposed to inflation risk.
“The editorial content here is not provided by any of the companies mentioned, and has not been reviewed, approved or otherwise endorsed by any of these entities. Opinions expressed here are the author’s alone. This email may contain links through which we are compensated when you click on or are approved for offers.”
from .
Copyright © 2004-2021 MyMoneyBlog.com. All Rights Reserved. Do not re-syndicate without permission.
Related Posts