Vanguard Research recently released a whitepaper titled () and I was surprised to find it rather substantial – almost a short book on retirement income planning that provides valuable insight into their (growing!) financial advisory services. The focus is clearly about creating a sustainable income from your portfolio, not the usual stuff about growing your portfolio.
Focusing on income rather than account balances can lead to clearer decision-making in retirement.
Without a defined income plan, investors may spend too cautiously or risk drawing down their assets too quickly. With an income-focused framework, you can better understand how to turn your savings into spending by having a clearer view of:
– How much you can withdraw over time.
– How long your assets may need to last.
– How different risks can affect outcomes.
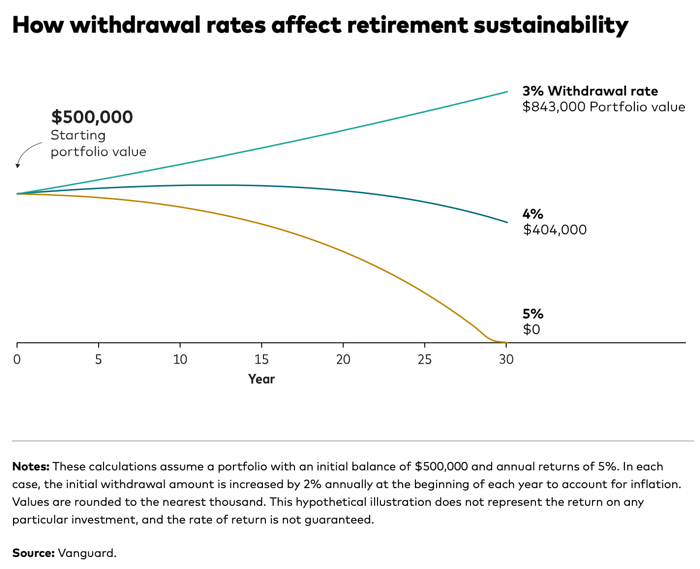
As a start, you have your sources of guaranteed income (pensions, annuities, Social Security) and roughly 3.5% to 4% of your portfolio, based on historical numbers:
Here are some of the recommended strategies to help stretch things further to create enough income for the rest of your lifetime. Some are more for those that really need to make some big, hard decisions in order to not run out of money, while others are more about marginal improvements.
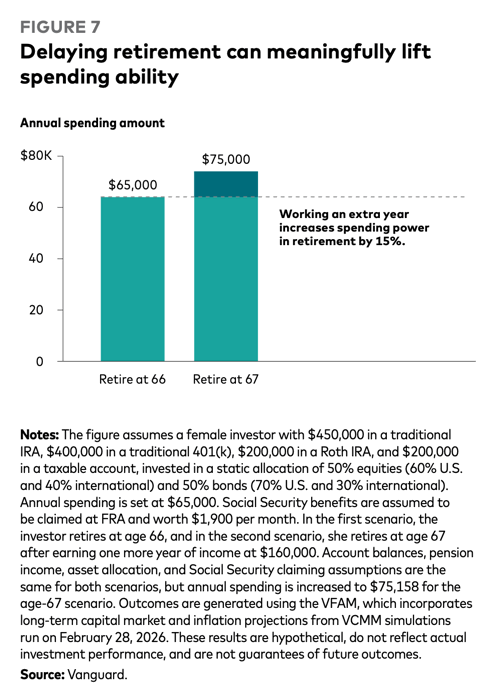
- Work longer. Not ideal, but powerful. You earn more, you also delay the start of Social Security claiming, and you have a shorter retirement period to cover.
- Dynamic spending. Rather than a fixed percentage withdrawal rate, dynamic spending extends the life of the portfolio by reducing withdrawals if there are poor market returns. There are many ways to implement this.
- Convert some assets to SPIA (single-premium income annuity). If you need to support a hard floor in your income to support essentials, an SPIA can help provide the reliable income needed.
- Tapping home equity. Something to consider if necessary to provide for essentials, especially later in retirement.
- Roth conversions. Converting tax-deferred investments to Roth when your marginal tax brackets are lower (like right after you stop working) can reduce your overall tax paid.
- Tax-efficient withdrawal strategy. In general, you should withdraw from taxable accounts
first, then tax-deferred, then save Roth for last.
If anything, this paper provides some good places to dig deeper when the time comes.
Related Posts